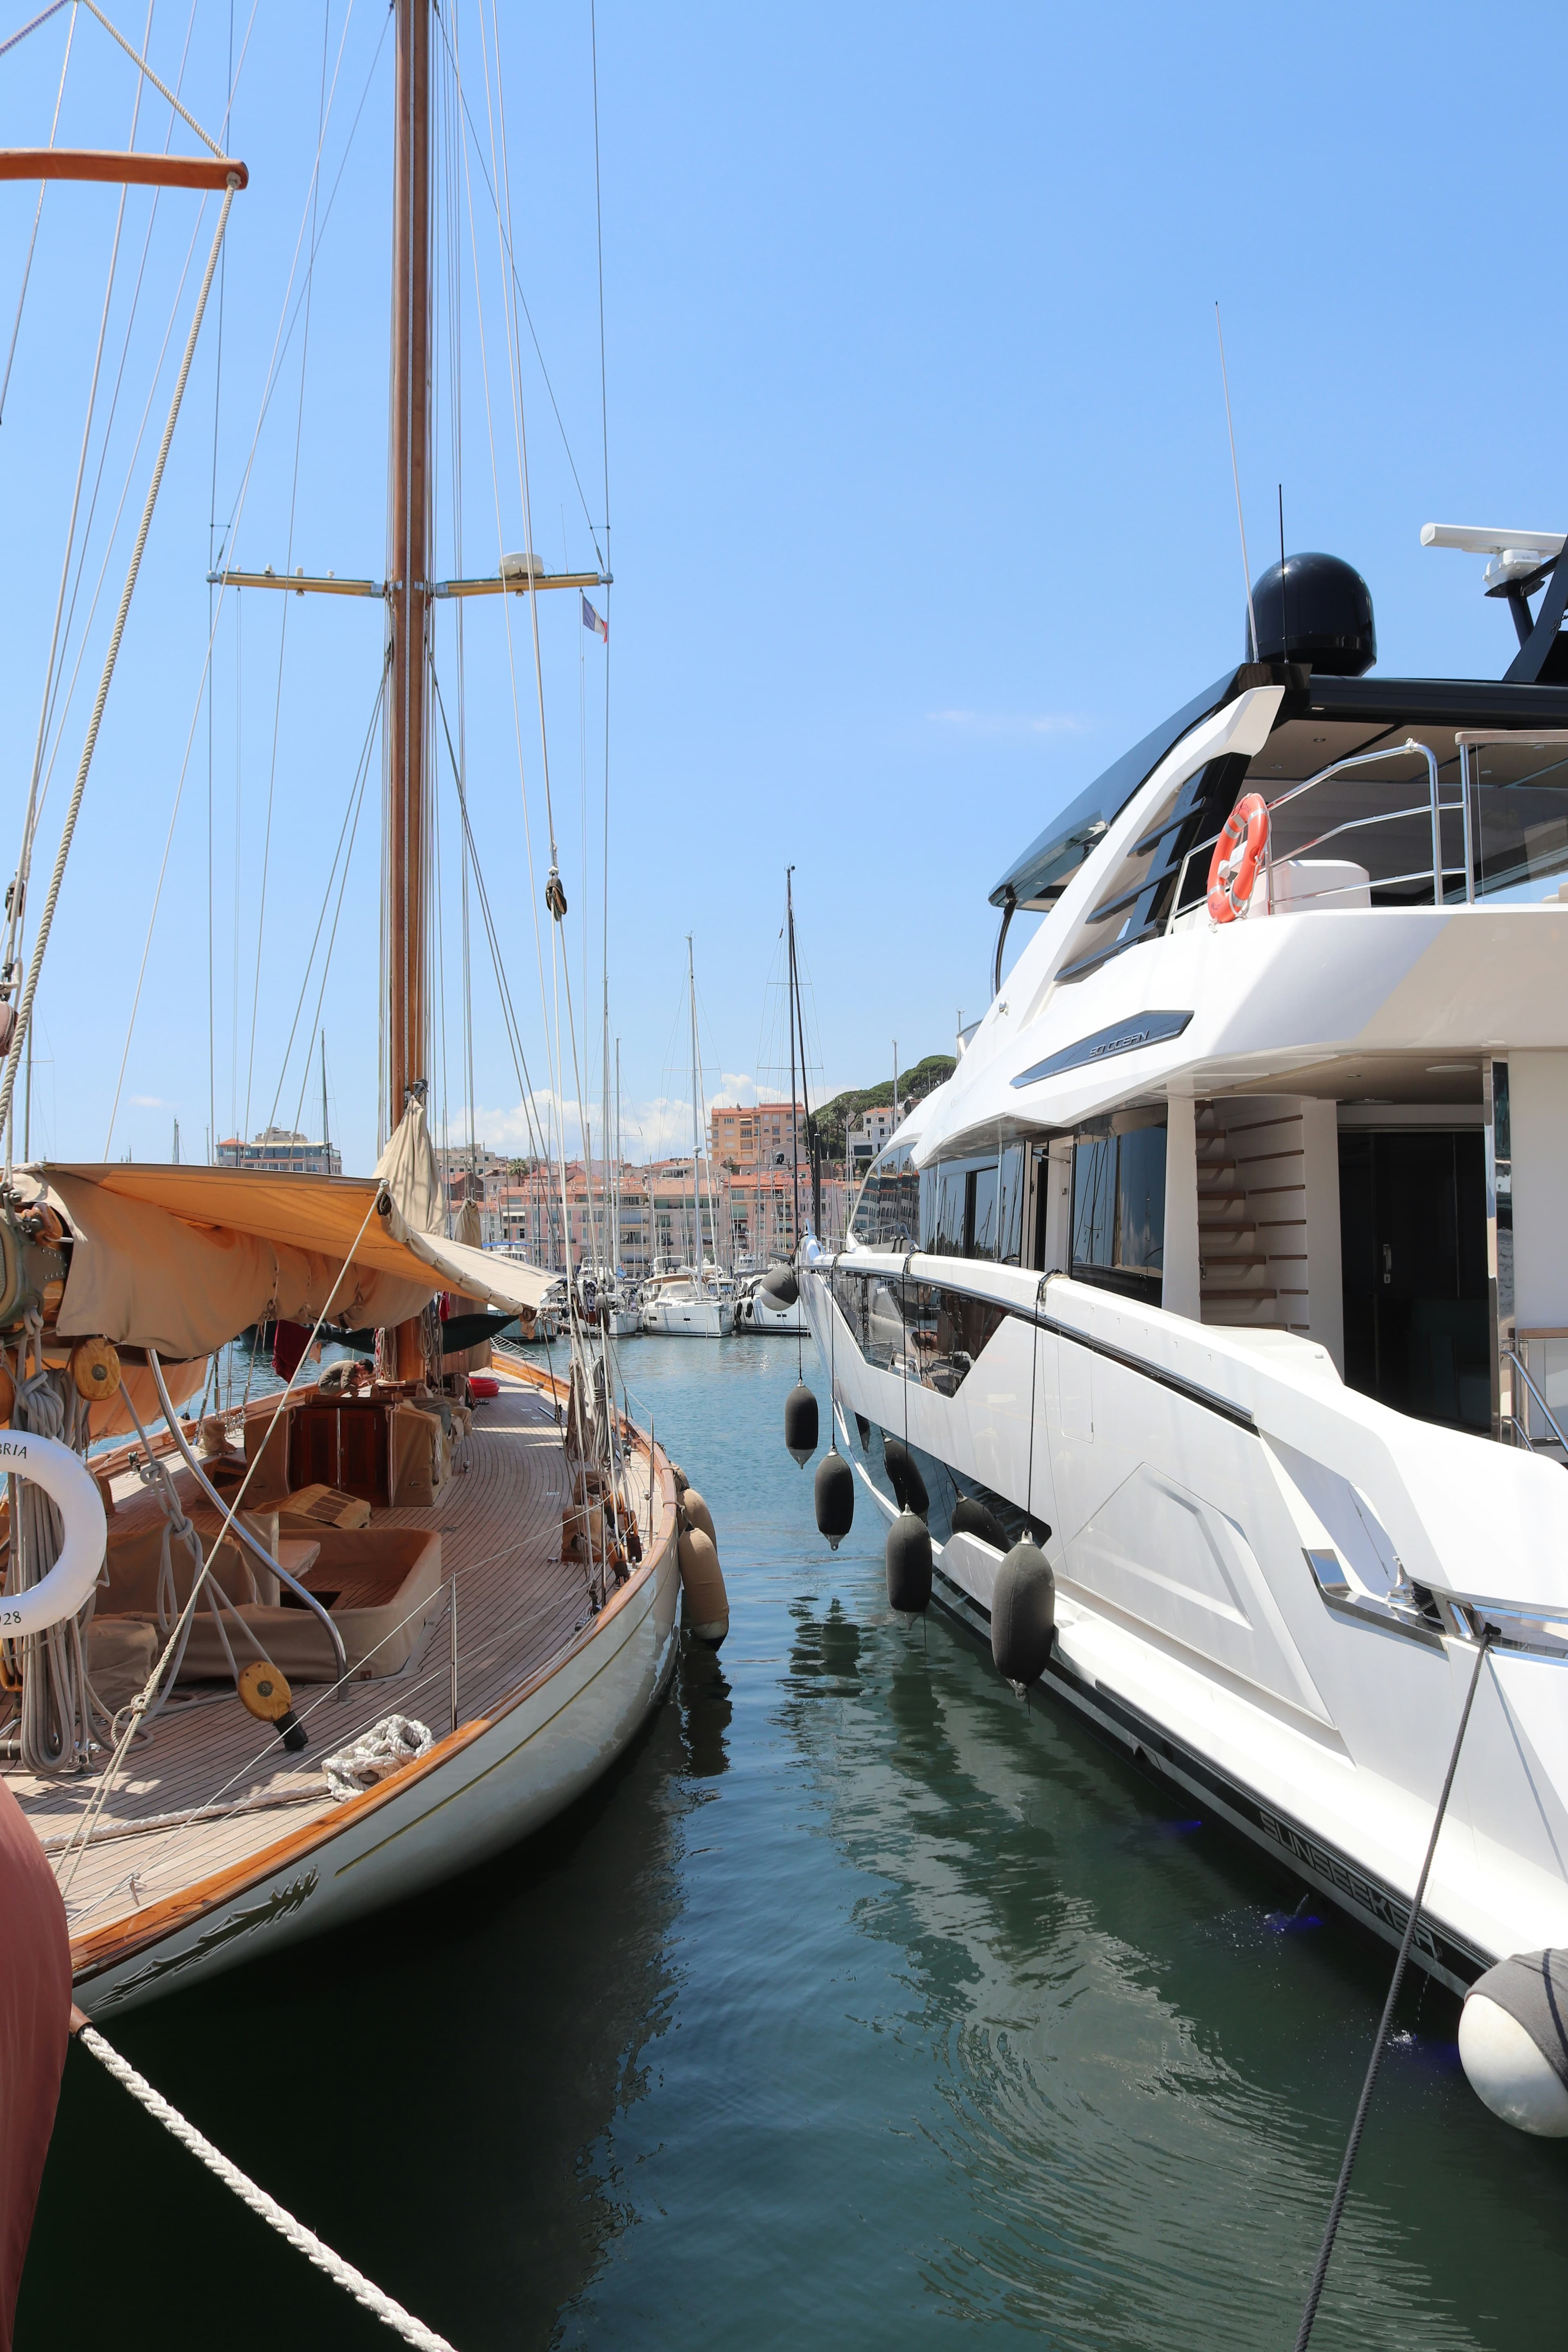
08
Motor versus sail
The structural decision few first-time buyers spend enough time on. Operating cost, environmental footprint, racing pedigree, and the case for sail.
The choice between sailing and motor is often presented as a question of taste. The framing is convenient for those selling either, and not the most useful for a buyer planning a decade of ownership.
The honest comparison runs across operating cost, carbon profile, intended cruising pattern, residual value, and a small but growing third path of hybrid and electric drive. This chapter walks each, then closes on the three threshold tests that tend to decide it.
The market is asymmetric. BOAT International’s 2026 Global Order Book records 69 sailing yachts among the 1,093 on order, about 6 percent of units; Camper & Nicholsons and SuperYacht Times brokerage data places sailing yachts at around 18 percent of the active over-30m fleet. The serious sailing yacht builders (Royal Huisman, Vitters, Baltic, Perini Navi, Wally) sit in a smaller category by units and a larger one by hold value.
Operating cost, line by line
A 50 metre sailing yacht runs meaningfully less than a 50 metre motor yacht of comparable build quality. The differential rarely surfaces in broker conversations because brokers handle the two segments separately. Practitioner ranges, from a Foreland archive of managed projects:
Fuel. A 50m motor yacht running 400 hours/year burns EUR 200,000 to 350,000 in diesel. A 50m sailing yacht operated primarily under sail burns EUR 60,000 to 120,000.
Crew. A 50m sailing yacht operates with 6 to 9 crew against 9 to 14 on a comparable motor. Variance on both sits mainly in the interior team. Sail-handling specialism on deck adds modest cost; the engine room runs lighter. Quay Crew 2025/26 records sailing yacht captain pay slightly below motor at equivalent length, although the experienced sailing yacht captain market is thinner.
Maintenance. Sailing yachts carry rigging and sail-wardrobe costs that motor yachts do not: full sail wardrobe replacement at 7 to 10 year intervals runs EUR 400,000 to 1.2 million, and standing rigging at 10 to 15 years runs EUR 250,000 to 700,000. Set against that, sailing yachts carry less main-engine wear, smaller stabiliser systems, and simpler hydraulic and HVAC loads, so net annual maintenance is broadly comparable; the cost shape differs.
Berths. Pricing is by length overall, so sailing and motor yachts of the same length pay roughly the same. A handful of marinas (Antibes, Saint Tropez, Newport, Saint Maarten) hold preferred slots for significant sailing yachts during regatta windows.
Total operating cost. A 50m sailing yacht at moderate use typically runs 70 to 85 percent of the equivalent motor figure. The differential narrows in the 24 to 40m band and widens above 60m where motor fuel and crew cost grow disproportionately.
We have the mainsail reefed and the J4 out. We’re surfing waves doing 20 knots, dolphins jumping out around us. There’s a thrill in that which you would never get on a motorboat.
The carbon profile, with the relevant nuance
Three regulatory and market shifts have changed the carbon conversation since 2020.
EU ETS Maritime is the most consequential, and narrower than often described. In force from 1 January 2024, it applies to ships of 5,000 GT and above that carry passengers or cargo for commercial purposes to or from EEA ports. Compliance is phased by emissions year: 40 percent of 2024 emissions (surrendered in 2025), 70 percent of 2025 emissions, and 100 percent of 2026 emissions onward, first due by 30 September 2027. A yacht in private use sits outside the system at any size. A yacht of 5,000 GT or more on commercial charter can fall inside it, and published guidance does not settle the position of charter yachts certified for 12 passengers or fewer. Very few yachts reach the threshold in any case (a 60m motor yacht is typically 700 to 1,200 GT). In July 2026 the European Commission proposed extending the system to selected ship types between 400 and 5,000 GT from 2031; the proposal does not name yachts, and negotiation runs into 2027.
The methane line added from 2026 matters most for liquefied natural gas (LNG)-fuelled vessels where methane slip is significant. For diesel-fuelled engines and diesel hotel-load generators on most yachts, methane emissions are negligible; the practical taxation effect remains on CO2.
The IMO 2023 Strategy (MEPC 80, Resolution MEPC.377(80)) sets a 20 percent well-to-wake GHG reduction by 2030 (striving 30), 70 percent by 2040 (striving 80), net zero by or around 2050, against 2008 levels. The strategy shapes the commercial shipping fuel transition that reaches yachting through fuel availability and cost. The IMO Net-Zero Framework, which would add a global fuel standard and emissions pricing for ships of 5,000 GT and above in international shipping, was approved in April 2025; a vote to adopt it was adjourned in October 2025 and resumes on 4 December 2026. If adopted it could not enter into force before 2028, and whether it would reach yachts is not settled. Closer to hand are the IMO emission control areas. The Mediterranean has required 0.10 percent sulphur fuel since May 2025. A new North-East Atlantic area, covering the waters of the United Kingdom, Ireland and Atlantic France, Spain and Portugal, enters into force on 1 September 2027, with low-sulphur fuel required there from September 2028 and NOx Tier III engines for ships contracted from 1 January 2027. A buyer contracting a new build in 2027 for Atlantic Europe should confirm with class how Tier III applies.
The most consequential near-term answer is hydrotreated vegetable oil. HVO is a paraffinic diesel made from waste fats and vegetable oils, a true drop-in replacement for marine gas oil: existing engines, fuel systems, and tanks accept it without modification. Lifecycle CO2 is 85 to 90 percent below fossil diesel; cetane above 70 gives cleaner combustion and a small power benefit. Bunker availability is strongest in the Mediterranean, weaker in the Caribbean and US East Coast, mixed elsewhere; it is priced at a premium over mineral diesel that varies widely by port and supplier. Feadship’s 84m Obsidian, delivered in 2023, was designed and sea-trialled to run on HVO; uptake among other quality builders has accelerated. For owners wanting a defensible carbon position without rebuilding the engine room, HVO is the easiest move available.
Methanol and hydrogen-fuel-cell drives are moving from concept to delivery; both require significant new-build engineering. Methanol-ready arrangements are appearing in the larger Northern European order books, and fuel cells are already in delivered hulls for hotel load and low-speed running: Sanlorenzo delivered a 50 metre yacht with a methanol reformer fuel cell in 2024, Feadship’s 118.8 metre Breakthrough carries hydrogen fuel cells, and Lürssen launched a 114 metre methanol fuel-cell yacht in 2025. For most readers, HVO and hybrid drive are the practical near-term options.
Capgemini’s 2024 World Wealth Report identifies sustainability as a major concern for next-generation HNWIs. A yacht is conspicuous in a way a family office’s liquid portfolio is not; a growing number of principals want the carbon question answered in advance. A serious 50m sailing yacht programme runs 60 to 70 percent below the comparable motor programme on annual carbon footprint (Royal Huisman published data plus aggregated practitioner numbers). The gap is large, and durable.
Sailing yachts are not zero-carbon. They are structurally cleaner than motor yachts by a margin that family offices have begun to model rather than apologise for.
Hybrid and electric drive, the third path
Hybrid propulsion has moved from concept to delivery and reshapes the motor-versus-sailing decision in ways the trade press has not fully caught up with. Two builders are the published reference points.
Heesen Yachts’ hybrid programme is the deepest commercial deployment of parallel diesel-electric propulsion in production yachts. The 50 metre FDHF aluminium series (Home, Amare II, Project Orion early 2025) pairs two main diesels, two diesel generators, and two electric motors operable separately or in combination. Owners use electric for harbour transits, anchor approaches, and short coastal hops; diesels for passage. Owners report meaningful annual fuel reductions; the operational character is closer to a sailing yacht’s silence at anchor than to conventional motor.
Royal Huisman has taken the deeper-engineering route. Aquarius II, a 65 metre sailing yacht delivered in 2025, integrates semi-hybrid power generation with battery and load smoothing, supported by hydro-generators that trickle-charge under sail. The shipyard’s AERA concept (with Rondal, Artemis Technologies, Cor D. Rover Design) layers wind-assisted propulsion, hydro-generation, and a hydrogen fuel cell for up to 72 hours of zero-emission operation, with a 580 kWh battery bank sized to run hotel load silently for around 11 hours. AERA remains a concept; the underlying technologies are in delivered hulls.
A third reference point sits at the wind-and-solar end of the spectrum. Captain Arctic, a 70 metre polar expedition ship for 36 passengers built for the French operator Selar at Chantier Naval de l’Ocean Indien in Mauritius, floated out in August 2026 for delivery late in the year and is chartered through Pelorus Yachting. She carries two rigid aluminium sails faced with around 1,860 square metres of photovoltaic panels, electric propulsion that doubles as hydro-generation under sail, and Bureau Veritas certification of a 90 percent CO2 reduction against comparable vessels. The cruising programme is Norway, Svalbard, and Greenland; the captain is Sophie Galvagnon, with seventeen years in the Arctic as captain and ice pilot. The ship does not occupy the same operational envelope as a conventional motor yacht of the same length; it sits at the new edge of the hybrid path, closer in profile to Royal Huisman’s AERA concept than to the Heesen FDHF programme (Gayle Patterson, Pelorus Yachting, in The Superyacht Report, Q2 2026).
For the buyer thinking about the next ten years, hybrid and electric capability is now a question to ask of any new build, sailing or motor. Bering Yachts, Wider, Sanlorenzo (SX series), Lürssen, Feadship, and Oceanco all have hybrid hulls in build or delivered. The decision is no longer two-way; it is three-way with hybrid sitting between.
BoatPro’s 2026 order-book engine breakdown shows the magnitude side of the same story. Diesel remains overwhelmingly the dominant propulsion among in-build hulls, hybrid orders are rising sharply year-on-year off a small base, diesel-electric is in a similar trajectory, and pure electric is flat at a handful of units. The direction is clear; the share is still small. A new-build buyer asking the hybrid question in 2027 is still asking it earlier than most of the order book, not late.
A fourth pattern is the multihull. Catamarans are the only sub-segment of the sailing market reporting unit growth among UHNW buyers (Fraser Yachts, May 2026). Baltic Yachts has a catamaran in build for 2027 delivery; the yard frames the multihull as the first stage of crossover between motor and sail, offering the flat platform a motor-side buyer expects on a yacht that runs primarily under sail. The category is too small to characterise residual behaviour reliably, and the structural argument that the multihull is the natural compromise between the two propulsions sits in early evidence and warrants tracking.
A fifth, separate from the propulsion debate, is the explorer: SeaXplorer, Damen Yacht Support, and the high-latitude end of the Northern European order book, where the cost shape is determined by self-sufficiency rather than hospitality.
A motor yacht in Antibes has a guest list. An explorer has a history.
The instinct is not yacht-specific. Knight Frank’s Wealth Report 2026 carries the same observation from outside the industry. Erwan Rambourg, Global Head of Consumer & Retail Equity Research at HSBC, frames the broader generational shift as a rejection of repetition rather than of luxury itself — “Luxury brands became way too expensive and way too repetitive. They lost interest in a broken value proposition.” Bernhard Bohnenberger of Discover Collection, opening a low-density retreat on Oman’s Musandam Peninsula, locates the same instinct in travel:
Affluent travellers have grown weary of interchangeable five-star resorts that could exist anywhere. What they increasingly seek are environments that feel location-specific, difficult to access and intellectually engaging.
What that frame says about the explorer programme: it is a yacht built to be hard to replicate. A buyer attracted to the profile is buying the difficulty as well as the capability.
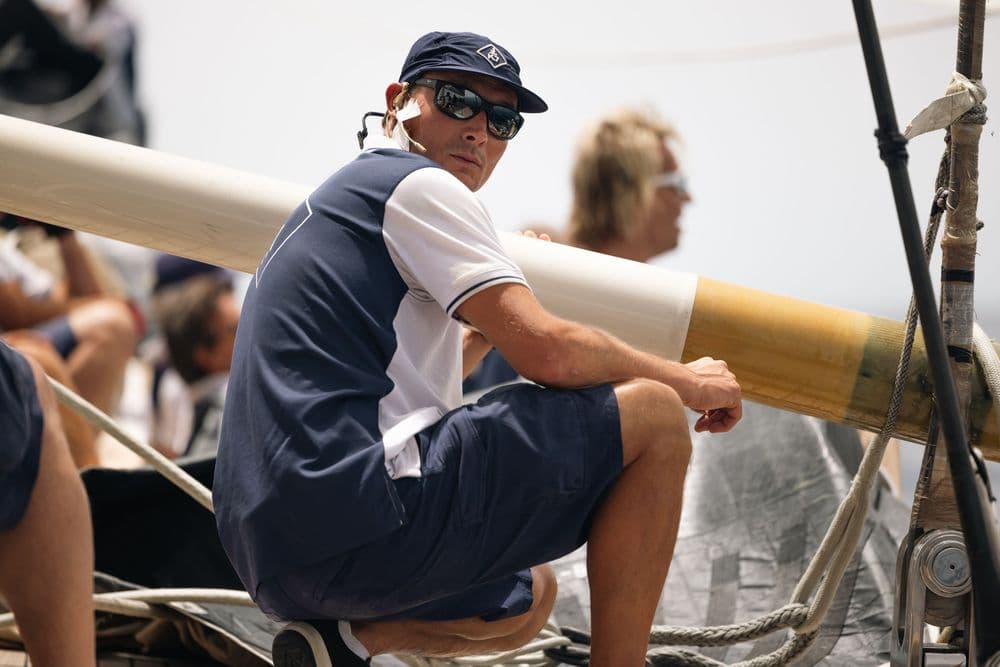
Racing pedigree and value retention
Racing pedigree is underweighted in trade-press coverage of the segment and does more to support residual values at the top than any other single factor. Three circuits matter.
The J Class. Nine hulls active: three surviving originals (Velsheda, Shamrock, Endeavour) refitted for cruising and racing, plus six modern builds since 2003 (Ranger, Rainbow, Hanuman, Lionheart, Topaz, Svea). They race at Newport, Saint Barths Bucket, Maxi Yacht Rolex Cup, J Class World Championship. A further hull is reported in build at Brodotrogir, Croatia. Provenance, regatta access, and the closed class support residuals well above comparable cruising sailing yachts; a hold-forever asset for the families who own them.
The Maxi and Wally circuit. Maxi Yacht Rolex Cup (Porto Cervo), Voiles de Saint Tropez, Loro Piana Superyacht Regatta, Antigua Bermuda Race form the Maxi season. Wally hulls (Wally B, Wallygator, Wally 80 to 130) trade actively with strong residuals at the top.
The RORC calendar. Fastnet, RORC Caribbean 600, Middle Sea Race, Transatlantic Race. Offshore-capable yachts (typically 18 to 30m) for which racing pedigree adds 10 to 25 percent premium on resale over a comparable cruising hull (broker-aggregated data).
Two 2025 reference points illustrate segment health. Edmiston and Nautor Swan announced an alloy sailing yacht range at the 2025 Palm Beach International Boat Show, designed by Malcolm McKeon Yacht Design (also responsible for the 83m Feadship Project Solent, on which Cecil Wright is acting as owner’s representative for summer 2027 delivery). Tom Cruise commissioned a Swan 108 in February 2025, a 33m carbon-fibre racing-capable sailing yacht at Nautor Swan, Jakobstad, estimated above USD 30 million. Committed capital and significant design houses are building modern sailing yachts at the top in numbers the order book does not yet show.
By May 2026, Palma International Boat Show added further evidence of segment differentiation. Will Bishop of Superyacht Partners describes the performance sailing yacht market between 28 and 34 metres as trading strongly, often off-market, while the 35 to 45 metre band sits noticeably softer (Superyacht Investor, May 2026). Baltic Yachts presented Canova (43m, asking EUR 29.8 million, the owner’s fifth Baltic yacht) and Liara (34m, the Baltic 112). Southern Wind delivered SW108 Kalantis in February 2026 against an August 2024 contract; the yard reports its next available build slot is in 2028, the new owner is in his 30s, and the average ownership age across the three Southern Wind hulls at Palma sits in the late 40s. The age curve at the buyer end of the sailing yacht market is moving down.
Georges Bourgoignie of Fraser added the broker-side counterweight on the same coverage:
It’s so much more work to sell a sailboat, but it’s somehow more fulfilling. But it’s tough and getting tougher.
Broker commentary describes the sailing segment as healthier than the headline unit-share suggests, and harder to transact; both can be true.
Stefan Zimmermann Zschocke, CEO of Oyster Yachts, on the Superyacht Investor London panel in April 2026, located the buyer-side instinct behind the sail demand at the top of the segment:
We’re seeing more and more younger centi-millionaires coming. So these centi-millionaires, at least in our niche, they want to have a purpose … either authenticity, adventure or community.
The Oyster World Rally, the owner-driven circumnavigation Oyster runs roughly every other year, is the operational expression of the purpose Zimmermann Zschocke describes: authenticity, adventure or community. The retention thesis the segment uses sits on top of it: the buyer who completes one rally tends to commission the next, larger boat.
Bang for buck, on a 35 metre
For a buyer in the 24 to 40 metre band, a sailing yacht typically delivers more cruising days per pound or euro than a motor yacht of comparable build quality.
A new build 35m sailing yacht from a quality builder (Pendennis, Vitters, Baltic) runs EUR 12 to 22 million; a comparable 35m motor yacht runs EUR 18 to 30 million. Capital differential 20 to 35 percent in favour of the sailing yacht. Annual operating cost runs 70 to 85 percent of the motor figure. A EUR 1.5 million annual operating budget delivers 16 to 20 weeks of family use on a 35m sailing yacht against 12 to 14 weeks on the equivalent motor.
Depreciation. Quality sailing yachts hold value much better than comparable motor yachts in the 30 to 50m band (broker-aggregated data). Top sailing builders (Royal Huisman, Vitters, Baltic, Nautor Swan) show single-digit annual depreciation after year five, against 5 to 8 percent for top motor builders. Across a seven-year hold a 35m sailing programme runs 25 to 40 percent below the equivalent motor on total cost (capex plus opex minus residual). Brokers do not present this comparison because the two segments are sold by different desks.
Where the case for sail does not hold
There are owners for whom a sailing yacht is the wrong answer, and the cases are worth naming.
Sailing yachts ask more from the operation: sail-handling expertise on the deck team, weather routing discipline, and itineraries that bend to the wind. An owner who needs to cross the Atlantic on a fixed schedule with no flexibility on the weather window is not a sailing-yacht owner. An owner comfortable with a 36 to 60 hour weather window for a transatlantic is.
Sailing yachts are heavier on the body and on time. A motor yacht delivers a steady ride at displacement speed. A sailing yacht heels, accelerates, decelerates, and asks more of the people aboard. Older owners, owners with mobility constraints, and owners who use the yacht primarily for entertaining rather than cruising are often better served by a motor yacht (or a hybrid one).
The supply side is thinner. There are fewer high-quality sailing yacht builders, fewer slot opportunities, and a smaller pool of comparable hulls in the brokerage market. A buyer who wants a 35 metre sailing yacht in 2027 has a shorter list of credible options than a buyer looking for a 35 metre motor yacht. The market is healthy; it is small.
Three threshold tests
Three questions tend to decide it for any specific buyer.
First, what does the cruising calendar look like? An owner whose programme depends on fixed-date passages with no weather contingency is on the motor or hybrid side. An owner with a season of cruising flexibility is on the sailing-yacht side, or has a real choice across all three.
Second, how exposed is the buyer to the carbon question? A principal whose family office, foundation, or public profile pulls at the carbon line will sit closer to the sailing yacht or hybrid side. A principal for whom carbon is not a board-level conversation will weight the cruising-calendar question more heavily.
Third, what is the seven-year arithmetic? Run capex, opex, depreciation, and residual against the buyer’s actual use case before defaulting either way. Most first-time buyers default to motor without doing the comparison; some of them are right to, others are not.
The chapter does not arbitrate between motor and sail. It asks the comparison to be run on variables that move, with hybrid drive considered a third option rather than a footnote, and the regulatory weather watched rather than ignored.
We put four questions to Ella on sail at the top of the market: race week on a performance sloop, what she would specify differently with seven years’ operational experience, a passage that stands for the case for sail, and what life onboard takes from a family new to it. Answers are given on the record, lightly edited for length and clarity.
You raced a 35 metre Nautor Swan on the Maxi circuit earlier in your career. Walk us through a race week on that boat: what changed in the programme, who was on the rail, and what did the owner take from those seven days?
Your current boat — a 34 metre Baltic Yachts performance sloop — launched in 2019. What was specified at build that you would still recommend today, and what would you change with the benefit of seven years’ operational experience?
Take a passage you remember. Where were you, what were the conditions, and what is the moment from it that you would describe to a first-time owner weighing sail against motor?
We put three questions to Capt. Filippakis on the explorer and high-latitude angle: how the segment compares operationally with a conventional 50 metre Mediterranean motor programme, what Polar Code-certified operation actually requires of owner, crew, and build, and the honest case versus the romantic mistake for a first-time UHNW buyer attracted to the explorer profile. Answers are given on the record, lightly edited for length and clarity.
The Damen Yacht Support range and the SeaXplorer line are reportedly booked through Q4 2028 / Q1 2029 on certain models. Operationally, how does this segment compare with a conventional 50 metre Mediterranean motor programme?
What does Polar Code-certified operation actually require of the owner, the crew, and the build, that a Mediterranean-only programme does not?
For a first-time UHNW buyer attracted to the explorer profile, what is the honest case and what is the romantic mistake?
Motor versus sail, by the numbers
Trade press treats the choice as taste; the data treats it as structural. Market share, operating cost, environmental footprint, and the racing market that supports value retention at the top of the segment.
Market share, on the published record
| Sail | Motor | |
|---|---|---|
| Order book 2026 share | 69 of 1,093 (about 6%) | 837 motor and 101 explorer of 1,093 |
| Active over-30 m fleet share | ~18% | ~82% |
| Major builders | Royal Huisman, Vitters, Baltic, Perini Navi, Wally, Pendennis, Nautor Swan | Lürssen, Feadship, Oceanco, Heesen, Sanlorenzo, Azimut Benetti, Codecasa, CRN |
Operating cost, 50 m comparable
| Cost line | 50 m motor | 50 m sail |
|---|---|---|
| Fuel | EUR 200–350 k | EUR 60–120 k |
| Crew (12–16 motor / 9–12 sail) | EUR 1.6–2.2 m | EUR 1.2–1.7 m |
| Maintenance and repair | EUR 600–900 k | EUR 500–800 k (plus rigging / sail wardrobe) |
| Insurance | EUR 350–550 k | EUR 280–450 k |
| Berths and marina fees | EUR 280–420 k | EUR 280–420 k |
| Total annual operating cost | EUR 3.0–4.5 m | EUR 2.3–3.5 m |
Annual operating cost on a 50 metre, motor against sail
A 50 metre sailing yacht typically runs 70 to 85 percent of the comparable motor cost. Crew, fuel, and insurance are the lines that move.
Capital and depreciation, 35 m comparable
| Sail (35 m, top builder) | Motor (35 m, top builder) | |
|---|---|---|
| New build entry price | EUR 12–22 m | EUR 18–30 m |
| Depreciation after year 5 | Single-digit % annually | 5–8% annually |
Environmental footprint and EU ETS exposure
| Yacht profile | Typical GT | EU ETS exposure |
|---|---|---|
| 60 m motor | 700–1,200 GT | Below threshold |
| 80 m motor | 2,000–2,800 GT | Below threshold |
| 90 m motor | Around 5,000 GT | Inside only if 5,000 GT or more and on commercial charter |
| 110 m+ motor | Above 5,000 GT | Inside only if on commercial charter; private use is outside |
| 50 m sail | 300–600 GT | Below threshold |
| Annual carbon footprint, 50 m sail vs 50 m motor | Comparable use | Sail roughly 60–70 percent below motor |
EU ETS Maritime exposure, by yacht profile
The EU ETS extension from 1 January 2024 applies to ships of and above 5,000 GT. Compliance phased 40 percent in 2025, 70 percent in 2026, 100 percent from 2027.
- BOAT International Global Order Book 2026. Sail share of order book; major sail and motor builders.
- EU Commission FAQ, EU ETS for maritime transport. Carbon market extension to maritime, in force from 1 January 2024; compliance phased 40 / 70 / 100 percent across 2025 to 2027.
- IMO 2023 Strategy on Reduction of GHG Emissions from Ships. Resolution MEPC.377(80), adopted at MEPC 80, July 2023. Targets: 20 percent (striving for 30 percent) by 2030, 70 percent (striving for 80 percent) by 2040, net zero by/around 2050.
- Capgemini World Wealth Report 2024. Sustainability identified as a top-three concern for next-generation HNWIs.
- Royal Huisman published sustainability commentary. Sail vs motor carbon footprint comparison; HVO and methanol-ready new builds.
- Superyacht Investor, May 2026. Rob Hodgetts, “Palma finds groove in search for sailing’s new generation.” Palma 2026 segment data, Baltic and Southern Wind reporting, multihull growth, Sanlorenzo buyer-meeting volume.
- Foreland Marine project archive. Operating cost ranges across managed sail and motor projects.
Running the comparison, before defaulting to motor.
A reference for the buyer at the point of choosing between motor, sailing yacht, and hybrid drive.
First-time buyers commonly default to motor. The items below are the variables on which the comparison turns.
The threshold tests
An honest read of the cruising calendar. Are the buyer’s seasons fixed-date and inflexible, or is there room for weather-window planning of 36 to 60 hours on transatlantics?
Fixed-schedule cruising tilts toward motor or hybrid. A flexible season opens the sailing yacht and hybrid options.
A position on the carbon question, set against the principal’s family office, foundation, or public profile.
Sailing yachts and hybrid programmes carry a lower carbon position than conventional motor yachts.
The seven-year arithmetic, run on paper, across capex, opex, depreciation, and residual.
Sailing yacht builders (Royal Huisman, Vitters, Baltic, Perini Navi) typically come in 25 to 40 percent below the equivalent motor programme on total seven-year cost.
Operating cost comparison, on a 50 m
Annual fuel projection, sailing yacht against motor. EUR 60 to 120 k for the sailing yacht, EUR 200 to 350 k for the motor at 400 cruising hours.
Crew complement and pay, sailing yacht against motor. 9 to 12 crew on a 50 m sailing yacht, 12 to 16 on a comparable motor.
Maintenance shape: rigging and sail wardrobe reserves on the sailing yacht set against engine wear and stabiliser systems on the motor. Net annual maintenance is broadly comparable; the cost shape differs.
Total annual operating cost. Sailing yacht typically 70 to 85 percent of the motor figure on equivalent length and use.
Carbon and regulation
EU ETS Maritime exposure. The system applies only to ships of 5,000 GT and above used for commercial passenger or cargo transport; a privately used yacht is outside it at any size.
Confirm the yacht’s GT, commercial or private status and passenger certification with the flag and the yacht lawyer. A July 2026 Commission proposal to extend the system below 5,000 GT does not name yachts.
HVO availability at the buyer’s home cruising port. HVO is a drop-in diesel replacement at 85 to 90 percent lifecycle CO2 reduction; bunker availability is strongest in the Mediterranean.
If new build, the emission control areas the yacht will cruise and the NOx Tier III dates that apply there, whether the engine maker approves HVO, and any methanol-ready or fuel-cell specification. Available from the larger Northern European yards on request.
The hybrid third path
Whether hybrid drive (Heesen FDHF, Sanlorenzo SX, and equivalent programmes) has been priced into the comparison alongside motor and sailing yacht.
Hybrid drive sits between motor and sailing on cost and carbon profile.
Battery hotel-load capability on the relevant new build candidates, with the capacity in kWh and the hours of silent running it supports.
The decision
A written summary of the comparison, signed off by the buyer and the independent adviser before any broker engagement on the chosen path.
Acceptance, on paper, of the residual case for whichever path is chosen.
The page is designed to print onto a single A4. Complete in writing before approaching any broker on the chosen path.
Open the printable checklistGlossary terms in this chapter
MARPOL Annex VI
International Convention for the Prevention of Pollution from Ships. Annex VI covers air pollution including SOx, NOx, particulate matter, and CO2 from yachts.
EU ETS Maritime
EU Emissions Trading System for shipping, in force from 2024 and phased in through 2026. Applies to commercial vessels above 5,000 GT entering EU ports.
Tier III emissions
MARPOL Annex VI NOx emission standard for engines installed on vessels constructed after 1 January 2016 operating in designated NOx Emission Control Areas.
Polar Code
International Code for Ships Operating in Polar Waters. Mandatory IMO framework covering vessel design, equipment, and operations in Arctic and Antarctic waters.
Frequently asked
- Is it cheaper to own a sailing yacht than a motor yacht?
- On a 50 metre yacht at 400 cruising hours per year, the sailing yacht runs EUR 60,000 to 120,000 on annual fuel against EUR 200,000 to 350,000 for the equivalent motor yacht. Crew complement is 9 to 12 on the sailing yacht against 12 to 16 on the motor. Quality sailing yacht builders such as Royal Huisman, Vitters, Baltic, and Perini Navi typically come in 25 to 40 percent below the equivalent motor programme on total seven-year cost (capex plus opex minus residual). The cost shape differs but net annual maintenance is broadly comparable.
- What is a hybrid superyacht?
- Hybrid drive combines diesel power with electric motors and a battery hotel-load capability, allowing the yacht to operate at low load on battery power and dock without the generator running. Heesen’s FDHF (Fast Displacement Hybrid Format), Sanlorenzo’s SX line, and equivalent programmes from Lürssen and Royal Huisman are the production references. Royal Huisman’s 65 metre Aquarius II, delivered in 2025, is the sailing reference for semi-hybrid generation with battery load smoothing. Hybrid drive sits between motor and sailing on cost and carbon profile.
- Does the EU ETS apply to private superyachts?
- Only in limited cases. EU ETS Maritime applies to ships of 5,000 GT and above carrying passengers or cargo for commercial purposes. A privately used yacht is outside the system at any size, and most yachts, including 60 to 80 metre motor yachts, are far below 5,000 GT in any case. A very large yacht on commercial charter can fall inside it. The share of emissions paid for rose from 40 percent (2024) and 70 percent (2025) to 100 percent from 2026 emissions onward. A Commission proposal of July 2026 would bring some ship types of 400 to 5,000 GT into the system from 2031; yachts are not among those named. HVO (hydrotreated vegetable oil) is a drop-in diesel replacement with a lifecycle CO2 reduction of up to 90 percent where certified waste-derived supply is available.
“Motor versus sail,” The First Owner’s Reference, 1st Edition, 2027.
Foreland Marine, “Motor versus sail,” in The First Owner’s Reference, 1st Edition (2027), Chapter 08, https://firstownersreference.com/08-motor-versus-sail.